philosophy & process
A disciplined process shaped by the Founders' three decades of hands-on origination and servicing experience.




Our Philosophy.
Operator-Investor Mentality

While other credit managers may only allocate capital, Scythian seeks to build the businesses the capital runs through.
Hired, trained and assembled origination teams from the ground up
Developed pricing engines and econometric market tiering tools
Managed loan servicing and capital markets relationships with major bank counterparties
Founders built loan origination and acquisition platforms at previous firms from a standing start into billions of dollars in annual volume
Wall Street Toolkit, Main Street Relationship
Institutional rigor paired with local speed.
Institutional capital markets fluency: securitization, structured finance, and execution at scale
Founders have decades of experience building and running real estate lending platforms, from origination through servicing
Long-standing broker and sponsor relationships help to surface deals before they reach a broad market
Long-Term Thinking, Every Decision
Decisions are weighed across three time horizons: current year, three years out, ten years out.
That approach shapes how the firm evaluates hires, technology, investments, and business lines
Decisions are made to compound over cycles, not just perform in the current one
Built for Cycles, Not Conditions
Single-strategy lenders are exposed to whichever part of the cycle hurts them most. Scythian’s founders have navigated multiple credit cycles.
Capital-intensive bridge loan originations and acquisitions, paired with capital-light, government-licensed businesses
Capital-light fee income and opportunistic acquisitions continue when credit markets tighten and origination volume slows
Strategy designed to reallocate as the environment shifts, not just absorb the shift
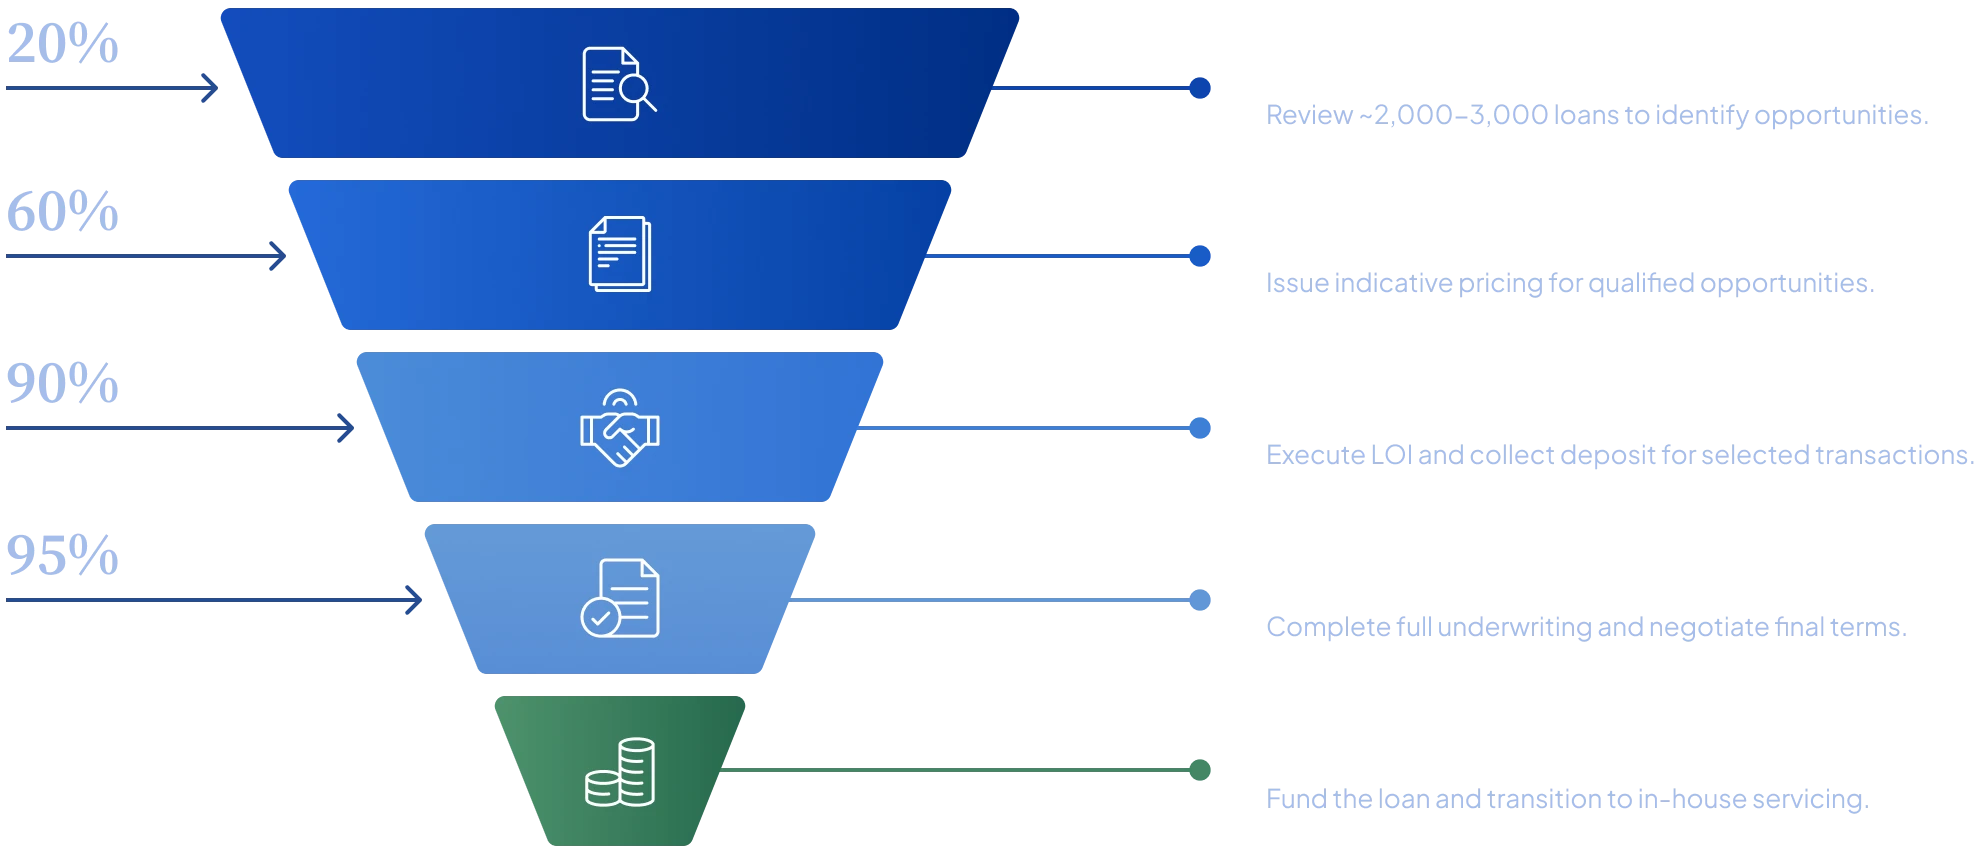
A disciplined process, built for results.
The process depicted above is illustrative and assumes a team of 6–8 seasoned originators at a $4–5B run rate. Percentages shown represent hypothetical stage-to-stage conversion rates. This information does not represent Founder performance or performance of Scythian or its affiliates and should not be viewed as indicative of future results.
A disciplined process, shaped by three decades of Founder experience in originating and servicing lower and middle market CRE at prior firms.
The following describes the origination and underwriting process that Scythian expects to implement and in some cases has commenced building out as its platform is built. As a newly formed firm, certain teams, systems, and infrastructure described in this section are not yet operational and may be modified as Scythian's team and infrastructure develop.
our PLANNED process
01. Sourcing

National origination coverage across primary and secondary markets, with originators expected to be placed across the Northeast, Southeast, Central, and Western U.S.
Deep, longstanding broker and industry contacts. CRM database of over 5,000 broker and industry representatives.
Leverage past strategic relationships to create robust alternative sourcing channels.
Web-based pricing engine available 24/7, so brokers get indicative terms without waiting on a call.
02. Preliminary Review & Structuring
Qualified deals move to the Loan Structuring team for originator submission review, pricing check, structuring, sizing, site visit if warranted and independent assessment of credit risk
LOI issued with limited conditions driven by detailed analyses performed upfront, not used as a placeholder
Term sheets viewed as commitments, transactions must close quickly and accurately
03. Underwriting
Once a term sheet is executed and a deposit received, a dedicated underwriter takes the deal through to closing
Underwriters have authority to recommend structural changes or decline a transaction
Underwriter compensation is generally expected to be tied to deal performance
Process is guided by PURE (Property Underwriting Risk Engine), a framework that follows the loan through its life
Underwriting covers five areas:
1. Real Estate: physical site visit is generally required on every deal, financial analysis, forward assumption stress testing
2. Location: GEOCipher, a market scoring model covering 40,000+ zip codes, assessed independent of sponsor or deal factors
3. Sponsor: local track record, financial wherewithal, in-person meeting generally required
4. Loan Structure: customized to the sponsor's business plan, with performance hurdles, cash management and recourse triggers built in
5. Diligence: third-party reports (appraisal, environmental, property condition assessment, crime, zoning, title), background checks on principals and entities
04. Investment Committee
No loan funds without Investment Committee approval
Committee includes Co-Founders, the Chief Credit Officer, and paid third-party advisors selected for specific expertise and is expected to include a Head of Loan Structuring at a later date
Members average more than 20 years of market experience across products and market cycles
05. Closing
Partner CRE law firm and origination counsel
Hybrid structure collapses the traditional multi-step closing process without sacrificing rigor
All loans fund through an established treasury team and systems
See it in action.
Our philosophy shapes how every loan moves through the platform. Get a glimpse of what that looks like across originations, acquisitions, and servicing.
Success stories from our
Sarah Brown

“The accounting team transformed our financial operations, providing invaluable insights and solutions that have significantly boosted our profitability. Their expertise is unmatched!.”
Sarah Brown
“The accounting team transformed our financial operations, providing invaluable insights and solutions that have significantly boosted our profitability. Their expertise is unmatched!.”
Sarah Brown
“The accounting team transformed our financial operations, providing invaluable insights and solutions that have significantly boosted our profitability. Their expertise is unmatched!.”